Fresno · Clovis · Central Valley
Your Business. Your Books. Our Priority.
Professional bookkeeping for Fresno, Clovis, and Central Valley businesses. We keep your records accurate and current so you can spend your time running the business.
| Item | Amount |
|---|---|
| Statement ending balance | 48,210.37 |
| + Deposits in transit | 3,450.00 |
| − Outstanding checks | (2,118.62) |
| Adjusted bank balance | 49,541.75 |
| Book balance | 49,541.75 |
| ✓Difference | 0.00 |
Illustrative example, not client data
What we do
Bookkeeping that keeps your numbers clean every month
From ongoing monthly books to untangling a year of backlog, we handle the recordkeeping so you have accurate financials when you need them.
Why outsource
Get your evenings back. Keep your books accurate.
Most owners we talk to are doing their books late at night or not at all. A dedicated bookkeeper changes that.
Hours back every month
Stop sorting receipts and matching transactions. Spend that time with customers, crews, and family.
Know where you stand
Monthly financial statements show what you earned, what you spent, and what's left.
Organized for tax season
Clean, reconciled books make the handoff to your CPA or tax preparer faster and simpler.
Less than a hire
Get consistent bookkeeping without adding payroll, training, or software seats.
Who we serve
Built for the businesses that keep the Central Valley running
Bookkeeping Built for Central Valley Businesses
See what we do in under a minute
Short films about the work we do for Central Valley business owners.
Messy books? Let's fix that.
Months of receipts and invoices, sorted, reconciled and turned into clear monthly reports.
Fresno & Clovis, this is for you
Contractors, restaurants, crews and shops across the Central Valley, with books they can count on.
Your time is worth more
Late nights with receipts and spreadsheets add up. Hand the books to us and get your evenings back.
How it works
From first call to clean books
Free consultation
A short call about your business, your software, and where your books stand today.
Proposal
A clear monthly scope and price. If you're behind, we include a cleanup or catch-up plan.
Onboarding
You sign, grant accountant access to QuickBooks Online, and upload records through a secure link.
Monthly close
We categorize, reconcile, and deliver your financial statements every month.
Questions
Frequently asked
Don't see yours? Ask during your free consultation.
Do I need to be in Fresno or Clovis?
We focus on the Central Valley, from Madera to Visalia and Hanford. Most work happens online, and we can meet locally when it helps.
Do you work in QuickBooks Online?
Yes. You keep ownership of your QuickBooks Online file and invite us as your accountant user. If you aren't using it yet, we can help you get set up.
My books are months behind. Can you help?
Yes. Catch-up and cleanup projects bring your records current, then you can move to monthly bookkeeping so it doesn't pile up again.
Do you do taxes?
We provide bookkeeping, not tax preparation. We keep your books organized so your CPA or tax preparer has what they need.
Will you ask for my bank passwords?
Never. We use accountant access in your software and bank feeds or statements you provide. We will never ask for bank or card login credentials.
How is pricing set?
Monthly bookkeeping starts at $250 per month, and every price is custom. Your exact fee depends mainly on your monthly transaction volume, plus the number of accounts and the reporting you need. We quote a flat monthly fee after the consultation.
Services
Bookkeeping services for Central Valley small businesses
Choose ongoing monthly support, a one-time cleanup, or a custom mix. Every engagement starts with a free consultation.
The House of Ledgers provides bookkeeping services. We do not provide tax preparation, audits, CPA services, or financial advisory services. See our Services Disclaimer.
Pricing
Flat monthly pricing, quoted after a free consultation
Pricing is custom, based mainly on your monthly transaction volume. You get a flat monthly fee, with no hourly surprises.
Essentials
Basic monthly bookkeeping for owner-operators and lean teams.
- Monthly transaction categorization
- Bank & credit card reconciliations
- Monthly Profit & Loss and Balance Sheet
- Email support
Growth
Bookkeeping plus expanded reporting for growing businesses.
- Everything in Essentials
- Accounts payable & receivable support
- Cash flow statement
- Month-over-month comparisons
- Quarterly review call
Premium
Comprehensive bookkeeping with additional support.
- Everything in Growth
- Class or job tracking
- Custom reports
- Monthly review call
- Priority response
Every price is custom. Your final monthly fee is based mainly on how many transactions you have each month, plus the number of bank and credit card accounts and the reporting you need. We confirm your exact price after a free consultation, before any work begins.
Need cleanup, catch-up, or something specific?
One-time projects and custom scopes are quoted separately.
Service areas
Local bookkeeping across the Central Valley
Based in Fresno and serving businesses throughout Fresno, Madera, Tulare, and Kings counties. Select a community.
About us
A Fresno bookkeeping firm for local business owners
Our mission is to help small business owners understand their finances, keep accurate books, and spend less time managing financial records.
Meet the founder
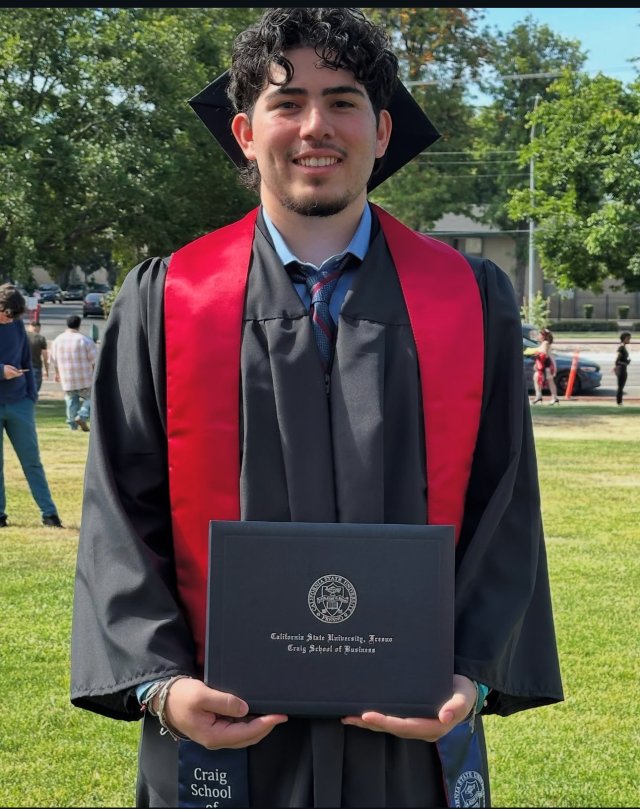
Donovan Nunez
Founder, The House of Ledgers
I grew up in the Central Valley. I've watched the family restaurants, contractors, farms and local shops here carry this region, often with owners doing the books late at night after a full day of work. I started The House of Ledgers to give those owners careful, organized bookkeeping without the cost of a full-time hire.
My background is in banking. Working in the banking industry showed me how much clean financial records matter for a small business, from getting a loan approved to knowing whether the business is actually making money. That shapes how I work: your books stay accurate, reconciled and ready whenever you, your banker or your CPA needs them.
I earned my finance degree from California State University, Fresno, through the Craig School of Business. When you work with The House of Ledgers, you work with me directly.
- EducationFinance degree, Fresno State, Craig School of Business
- ExperienceBanking industry
- RootsRaised in the Central Valley
Our values
How we work
Accuracy
Every account reconciled, every month. Clean numbers are the whole job.
Confidentiality
Your financial records stay private. We never ask for bank logins.
Plain language
We explain your reports in terms that make sense for your business.
Reliability
Books closed on schedule, and questions answered promptly.
Local roots
We know the seasons and pressures of Valley businesses because we work here too.
Trust
Why business owners trust us with their books
You own your data
Your QuickBooks file stays in your name. We work as your invited accountant user.
Secure document handling
Records are collected through secure upload, never over plain email attachments.
Clear agreements
Every client signs a written service agreement that spells out exactly what's included.
Resources
Bookkeeping tips for Central Valley business owners
Practical guides on organizing your finances, written for Fresno, Clovis and Central Valley business owners.
Free consultation
Let's talk about your books
Tell us a bit about your business. We'll follow up to schedule a free consultation, usually about 30 minutes.
- Based in
- Fresno, California
- Serving
- Fresno, Clovis, Madera, Sanger, Selma, Kingsburg, Visalia, Tulare, Hanford
- Email & phone
- (559) 331-2140
donovan@thehouseofledgers.com
Legal
Privacy Policy
Draft pending attorney review. Items in brackets will be filled in before launch.
Effective date: [Effective date]
The House of Ledgers LLC (“The House of Ledgers,” “we,” “us”) provides bookkeeping services to small businesses in California’s Central Valley. This policy explains what information we collect through thehouseofledgers.com and in providing our services, how we use it, and the choices you have.
1. Information we collect
Information you give us. When you request a consultation or contact us, we collect your name, business name, email address, phone number, industry, city, approximate monthly transaction volume, current bookkeeping software, services of interest, budget range, preferred consultation date, how you heard about us, and any notes you choose to include.
Client information. If you become a client, we also collect business details needed to perform bookkeeping, such as legal business name, entity type, tax identification number, contact details, billing information, and financial records you provide or authorize us to access (for example, bank and credit card statements, receipts, invoices, and access to your accounting software as an invited accountant user).
Information collected automatically. When you visit our website, our hosting provider and any analytics tools we use may collect technical data such as IP address, browser type, device type, pages viewed, referring website, and the date and time of your visit. [List analytics tool, if any, or state that none is used]
What we never ask for. We will never ask for your online banking or credit card usernames, passwords, or security codes. If anyone claiming to be us asks for them, do not provide them and contact us at (559) 331-2140.
2. How we use information
We use information to:
- Respond to inquiries and schedule consultations
- Prepare proposals and service agreements
- Provide bookkeeping services and deliver reports
- Send invoices and process payments
- Send service-related messages, such as reminders and document requests
- Send occasional educational or marketing emails, which you can opt out of at any time
- Maintain the security of our website and systems
- Comply with legal obligations
3. How we share information
We do not sell your personal information, and we do not share it for cross-context behavioral advertising.
We share information only:
- With service providers who help us operate, under confidentiality obligations. These may include [scheduling tool], [email provider], [payment processor], [e-signature provider], [secure file storage], our website host, and accounting software you use, such as QuickBooks Online.
- With your permission, for example when you ask us to send reports to your CPA, tax preparer, lender, or attorney.
- For legal reasons, when required by law, subpoena, or court order, or to protect our rights or the safety of others.
- In a business transfer, if our business is sold or merged, subject to this policy.
4. How we protect information
We use reasonable administrative, technical, and physical safeguards. These include encrypted connections (HTTPS), secure file-sharing tools instead of email attachments for financial documents, access limited to people who need it, multi-factor authentication on our accounts, and accountant-user access to your software rather than shared logins. No method of transmission or storage is completely secure, and we cannot guarantee absolute security.
5. How long we keep information
We keep prospect information for up to [24 months] after our last contact unless you ask us to delete it sooner. We keep client records for the length of our engagement and for [7 years] afterward, or longer if required by law, then securely delete or return them.
6. Your choices and rights
- Marketing email: use the unsubscribe link in any marketing email, or contact us.
- Access, correction, and deletion: contact us to ask what information we hold about you, to correct it, or to delete it. We may keep information we are legally required to retain.
- Do Not Track: our website does not currently respond to browser “Do Not Track” signals. [Confirm with your web host and analytics setup]
- California residents: California law may give you additional rights depending on the size and activities of our business. We will honor applicable requests.
7. Cookies
Our website may use cookies and similar technologies needed for it to function and, if enabled, to measure site traffic. You can block or delete cookies in your browser settings. [Update once hosting and analytics tools are chosen]
8. Children
Our website and services are for businesses and are not directed to children under 16. We do not knowingly collect information from children.
9. Links to other sites
Our website may link to other sites, such as scheduling or payment pages. Their privacy practices are governed by their own policies.
10. Changes to this policy
We may update this policy. We will post the new version on this page with a new effective date, and notify clients of material changes by email.
11. Contact us
The House of Ledgers LLC
[Mailing address]
Email: donovan@thehouseofledgers.com
Phone: (559) 331-2140
Legal
Website Terms of Use
Draft pending attorney review. Items in brackets will be filled in before launch.
Effective date: [Effective date]
These terms govern your use of thehouseofledgers.com, operated by The House of Ledgers LLC. By using the website, you agree to these terms. If you do not agree, please do not use the website.
1. What this website is
This website describes our bookkeeping services and lets you request a consultation. Using the website or submitting a form does not create a client relationship. A client relationship begins only when both parties sign a written service agreement.
2. Educational content
Articles, videos, checklists, and other content on this website are general information for small business owners. They are not accounting, tax, legal, or financial advice for your situation. See our Services Disclaimer.
3. Pricing and availability
Prices shown on the website are starting points and may change. Your actual price is set in your written proposal or service agreement. We may decline any engagement at our discretion.
4. Your submissions
When you submit a form, you agree that the information is accurate and that we may contact you about your request by email or phone. Please do not submit bank account numbers, passwords, Social Security numbers, or financial documents through website forms. We provide a secure method for documents once you become a client.
5. Acceptable use
You agree not to:
- Use the website for any unlawful purpose
- Submit false information or impersonate someone else
- Send spam, malware, or automated submissions
- Try to gain unauthorized access to the website or our systems
- Copy, scrape, or republish website content without permission
6. Intellectual property
The website’s text, design, logo, videos, and other content belong to The House of Ledgers LLC or its licensors and are protected by law. You may view and share links to our pages for personal or business reference. Any other use requires our written permission.
7. Third-party links and tools
The website may link to or use third-party services, such as scheduling, payment, or document-sharing tools. We are not responsible for their content, availability, or practices, and your use of them is governed by their terms.
8. No warranty
The website is provided “as is” and “as available.” To the fullest extent permitted by law, we make no warranties about the website’s accuracy, completeness, or availability, and we do not guarantee it will be free of errors or interruptions.
9. Limitation of liability
To the fullest extent permitted by law, The House of Ledgers LLC is not liable for indirect, incidental, special, or consequential damages arising from your use of the website. Our total liability for any claim related to the website is limited to $100. This section does not apply to services provided under a signed service agreement, which has its own terms.
10. Governing law
These terms are governed by California law. Any dispute about the website will be handled in the state or federal courts located in Fresno County, California.
11. Changes
We may update these terms by posting a new version with a new effective date. Continued use of the website after a change means you accept the updated terms.
12. Contact
The House of Ledgers LLC
[Mailing address]
Email: donovan@thehouseofledgers.com
Phone: (559) 331-2140
Legal
Services Disclaimer
Draft pending attorney review. Items in brackets will be filled in before launch.
The House of Ledgers provides bookkeeping services only. We are not a CPA firm and do not provide tax preparation, tax advice, audit, attest, legal, or financial advisory services.
Bookkeeping only
The House of Ledgers LLC provides bookkeeping services, including transaction recording and categorization, account reconciliation, preparation of internal financial statements, and accounts payable and receivable support. We are not a licensed certified public accounting firm, and our staff do not hold themselves out as CPAs.
No tax services
We do not prepare or file tax returns, give tax advice, or represent clients before the IRS or any state tax agency. We recommend you work with a licensed CPA, enrolled agent, or registered tax preparer for tax matters. With your permission, we will share your books with them.
No audit or assurance
Financial statements we prepare are for your internal use. They are not audited, reviewed, or compiled under professional accounting standards, and we express no opinion or assurance on them. Do not present them to lenders, investors, or government agencies as audited or reviewed statements.
No legal or financial advice
We do not provide legal, investment, or financial planning advice. Any general information we share, including on our website, in videos, or in articles, is educational and not advice for your specific situation.
Your responsibilities
Our work depends on the completeness and accuracy of the records and access you provide. You remain responsible for your business’s financial decisions, internal controls, tax filings, and compliance with laws that apply to your business. We are not responsible for detecting fraud, theft, or errors outside the scope of the services in your signed agreement.
Scope is set in writing
The specific services we perform, and any limits on them, are described in your signed service agreement. If anything in this disclaimer conflicts with your agreement, the agreement controls.
Tips
3 bookkeeping mistakes Fresno business owners make
Mixing personal and business spending, skipping reconciliations, and waiting until tax season. Here is how to fix each one.
Most small business owners in the Valley did not start a business to do bookkeeping. They started a landscaping crew, a taquería, a roofing company or a salon. The books get done when there is time, which usually means late at night or not at all.
That is understandable. But a few habits cause most of the trouble we see when owners finally hand their books to a professional. Here are the three most common, and what to do instead.
1. Mixing personal and business money
It starts small. A grocery run on the business card. A supply order on your personal card because it was the one in your wallet. Twelve months later, you have hundreds of transactions that someone has to sort into "business" and "not business," and every one is a judgment call.
Mixed accounts cause three problems:
- Your numbers are wrong. Personal spending inflates your expenses, so you can't tell what the business actually earns.
- Cleanup costs more. Sorting mixed transactions is slow, detailed work.
- It weakens your records. If you ever need to show a lender, a partner or your tax preparer what the business did, mixed accounts make that harder to prove.
The fix: open a dedicated business checking account and a business credit card, and run every business transaction through them. If you operate as an LLC or corporation, keeping business money separate also helps maintain the separation between you and the company. When you need to pay yourself, transfer money from the business account to your personal account and record it as an owner's draw or payroll, whichever fits how your business is set up.
2. Skipping monthly reconciliations
Reconciling means matching every transaction in your books to your bank and credit card statements, then confirming the ending balances agree. Many owners skip it because their software pulls in bank transactions automatically.
Bank feeds are useful, but they are not a reconciliation. Feeds can duplicate transactions, miss some entirely, or import a transfer twice, once from each account. Without a reconciliation, those errors stay hidden and pile up.
The fix: reconcile every bank and credit card account every month, shortly after the statement arrives. When an account is reconciled, the difference between your books and the bank is zero, and you can trust the balance. A month that won't reconcile is a sign something needs attention: a missing deposit, a duplicate expense or a payment that never cleared.
3. Waiting until tax season
For a lot of businesses, the books get done once a year, in a rush, because the tax preparer needs them. That approach has real costs:
- You make a full year of decisions without accurate numbers.
- Receipts and details are harder to remember a year later.
- Catch-up work in March and April is stressful and often more expensive.
- Problems such as an unpaid customer invoice or a duplicate vendor charge are found months too late to fix easily.
The fix: keep the books current every month. A monthly close means transactions are categorized, accounts are reconciled and you get a Profit & Loss and Balance Sheet while the information is still useful. When tax season comes, you hand your preparer clean, finished books instead of a shoebox.
Where to start
If you recognize your business in all three, start with the first one. Separating your accounts takes an afternoon at the bank and makes everything else easier. Then pick a date to start reconciling monthly, and decide whether you'll do it yourself or hand it off.
If your books are already months behind, read our guide on what to do when you're behind on your books.
This article is general information for small business owners, not tax, legal or financial advice for your situation.
Catch-up
Behind on your books? Here's what to do
A step-by-step way to get current without starting from scratch, and how to keep it from happening again.
Being behind on your books is more common than most owners admit. A busy season hits, a key employee leaves or the business simply grows faster than the paperwork. Before long it's been six months, or a year, since anything was entered.
The good news is that catching up follows a clear process. You don't need every receipt in perfect order to begin. Here's how to approach it.
Step 1: Stop the backlog from growing
Before you fix the past, make sure next month doesn't add to the pile.
- Use one business checking account and one business card for all business activity.
- Start saving receipts as you go. A photo on your phone, saved to one folder, is enough.
- If you use accounting software, connect your bank and card accounts so new transactions flow in automatically.
Step 2: Pick a starting point
Decide how far back you need to go. For most businesses this is the first day of the earliest year that isn't finished, usually January 1 of the current or prior year. If an earlier year was already completed and filed, start from its ending balances instead of redoing it.
Step 3: Gather your statements
Bank and credit card statements are the backbone of catch-up work. Every transaction your business made shows up on one of them. Most banks let you download past statements from online banking. If yours doesn't go back far enough, the branch can request older ones.
Collect statements for every account the business used during the catch-up period, including:
- Checking and savings accounts
- Credit cards, including any personal cards used for business
- Loans and lines of credit
- Payment processors such as Square, Stripe, PayPal or Venmo for business
Also pull together sales records, invoices you sent, bills you received and any payroll reports.
Step 4: Work month by month
Resist the urge to tackle everything at once. Take the first month, record and categorize every transaction, then reconcile each account to that month's statement. Only move on when the month balances.
Working this way keeps errors from carrying forward. If March won't reconcile, you know the problem is in March, not somewhere in the last fourteen months.
Step 5: Flag what you can't explain
You will find transactions you don't recognize. Don't guess and don't stop. Put them in a temporary "ask the owner" category and keep going. At the end, go through the list in one sitting. Most items get answered quickly once you see them together.
Step 6: Review the results
When every month is reconciled, run a Profit & Loss and Balance Sheet for the full period. Look for anything that seems off: a month with no sales, an expense category that seems too high or a loan balance that doesn't match the lender's statement. Then share the finished books with your tax preparer.
How long does catch-up take?
It depends on how many months you're behind, how many accounts you have and how many transactions run through them each month. A small service business a few months behind might take days. A busy restaurant a full year behind takes considerably longer. The best way to know is to look at your statements and transaction volume.
Keeping it from happening again
Once you're current, the most important step is staying current. Set a recurring date each month to categorize and reconcile, or hand monthly bookkeeping to someone else. Catching up once is manageable. Catching up every year is expensive and stressful.
If you'd rather not do the catch-up yourself, this is exactly the kind of project we take on. We'll look at your statements, give you a clear quote and bring your books current, then keep them that way.
This article is general information for small business owners, not tax, legal or financial advice for your situation.
Profit
Is your business actually profitable?
Why money in the bank isn't the same as profit, and the report that tells you the difference.
Ask a small business owner whether the business is making money, and many will check their bank balance. If it's higher than last month, things feel good. If it's lower, they worry.
Your bank balance is important, but it doesn't answer the question. A business can have a healthy balance and be losing money. It can also be profitable and short on cash. To know where you really stand, you need a different report.
Why the bank balance can mislead you
Money moves in and out of your account for reasons that have nothing to do with profit:
- Loans. When a loan is deposited, your balance goes up, but you didn't earn that money.
- Timing. A customer pays a large invoice this month for work done last quarter. Or you prepay six months of insurance at once.
- Customer deposits. A contractor collects a deposit before the job starts. The cash is in the bank, but the work, and the costs, are still ahead.
- Owner money. Money you put into the business, or take out of it, changes the balance without changing profit.
Any of these can make a month look better or worse than it really was.
The report that answers the question
The Profit & Loss statement, also called an income statement, shows what the business earned and what it spent to earn it over a period of time, such as a month or a year. At its simplest:
Revenue − Expenses = Net profit (or loss)
A well-kept P&L separates your costs into useful groups, so you can see not just whether you made money, but where it went.
Three numbers worth watching
Gross profit
Revenue minus the direct costs of delivering your product or service, such as materials for a contractor or food costs for a restaurant. Gross profit tells you whether your pricing covers the cost of the work itself. If gross profit is thin, no amount of cutting office expenses will fix it.
Net profit
What's left after all expenses: rent, insurance, software, vehicle costs, payroll and everything else. This is the clearest answer to "did the business make money?"
Profit after paying yourself
Many owners don't pay themselves a regular amount, so their P&L looks more profitable than the business really is. Try this: subtract what it would cost to pay someone to do your job. If the business only breaks even after that, it's worth knowing.
Profit by job, product or location
The overall P&L can hide a lot. A contractor might be profitable overall while losing money on one type of job. A restaurant might do well on weekdays and struggle on weekends, or the reverse. When your books track revenue and costs by job, service line or location, you can see which parts of the business carry the rest, and price or plan accordingly.
Make it a monthly habit
A P&L is only useful if it's accurate and current. That means transactions are categorized correctly and accounts are reconciled every month. Once that's in place, set aside 20 minutes each month to review it. Compare it to the prior month and the same month last year. Look for what changed and ask why.
Your P&L shows profit. To see whether you'll have enough cash to pay the bills, read our guide on what every small business owner should know about cash flow.
This article is general information for small business owners, not tax, legal or financial advice for your situation.
Cash flow
What every small business owner should know about cash flow
Seasonal swings, timing of payments and keeping a cushion, explained for Central Valley businesses.
Profit tells you whether the business is making money. Cash flow tells you whether you can pay the bills on Friday. They're related, but they are not the same, and plenty of profitable businesses have run into trouble because they ran out of cash.
Profit and cash are different
Here's a common example. A contractor finishes a $20,000 job in March and invoices the customer. On paper, March looks profitable. But the customer pays in May. Meanwhile, the contractor already paid for materials and labor in February and March. For two months, the business is profitable and short on cash at the same time.
The gap between when you spend money and when you collect it is where cash flow problems start.
Where cash gets stuck
Unpaid customer invoices
Money customers owe you is called accounts receivable. Every dollar sitting in receivables is a dollar you earned but can't use yet. Review who owes you at least monthly, and follow up on anything past due.
Inventory and supplies
Products on shelves, materials in the yard and food in the walk-in are cash you've already spent. Buying more than you need ties up money that could cover rent or payroll.
Loan payments
Here's one that surprises owners. Only the interest portion of a loan payment shows up as an expense on your Profit & Loss. The principal portion doesn't. So your P&L can show a profit while loan payments are quietly draining cash. If you carry equipment loans or a line of credit, account for the full payment when planning.
Seasonal swings in the Valley
Many Central Valley businesses don't earn money evenly across the year. Agricultural service companies follow planting and harvest schedules. Landscapers, pool services and HVAC contractors have busy and slow seasons. Retailers depend on the holidays. Restaurants feel the effect of school calendars, local events and the summer heat.
If your business is seasonal, the busy months have to fund the slow ones. The most common cash mistake we see is spending the strong months' cash as if every month will look like them.
Look back at last year's monthly bank deposits. Mark your slowest months, and set aside part of your busy-season cash to cover them.
Five habits that protect your cash
- Invoice right away. The sooner you invoice, the sooner you're paid. Don't wait until the end of the month.
- Make it easy to pay you. Accept card or online payments, and put clear due dates on every invoice.
- Collect deposits on large jobs. Deposits help cover materials and labor before the job is complete.
- Keep a cash cushion. Many owners aim to hold enough to cover a few months of fixed costs. Pick a target that fits your business and build toward it.
- Look ahead, not just back. Once a month, list the cash you expect to receive and the bills you expect to pay over the next 8 to 12 weeks. A simple spreadsheet works. It turns surprises into decisions you can plan for.
It all starts with accurate books
You can't manage cash flow from numbers you don't trust. When your accounts are reconciled every month and your invoices and bills are tracked, you can see exactly what's coming in, what's going out and when.
If you'd like help getting your books to that point, we're happy to talk it through in a free consultation.
This article is general information for small business owners, not tax, legal or financial advice for your situation.